KI-Beratung Beta

  • Produktbild: Distress Risk and Corporate Failure Modelling
  • Produktbild: Distress Risk and Corporate Failure Modelling

Distress Risk and Corporate Failure Modelling The State of the Art

85,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

This book is an introduction text to distress risk and corporate failure modelling techniques. It illustrates how to apply a wide range of corporate bankruptcy prediction models and, in turn, highlights their strengths and limitations under different circumstances. It also conceptualises the role and...

Beschreibung

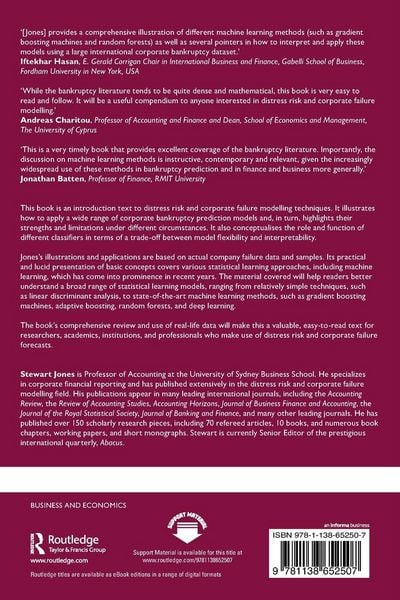
This book is an introduction text to distress risk and corporate failure modelling techniques. It illustrates how to apply a wide range of corporate bankruptcy prediction models and, in turn, highlights their strengths and limitations under different circumstances. It also conceptualises the role and function of different classifiers in terms of a trade-off between model flexibility and interpretability.

Jones's illustrations and applications are based on actual company failure data and samples. Its practical and lucid presentation of basic concepts covers various statistical learning approaches, including machine learning, which has come into prominence in recent years. The material covered will help readers better understand a broad range of statistical learning models, ranging from relatively simple techniques, such as linear discriminant analysis, to state-of-the-art machine learning methods, such as gradient boosting machines, adaptive boosting, random forests, and deep learning.

The book's comprehensive review and use of real-life data will make this a valuable, easy-to-read text for researchers, academics, institutions, and professionals who make use of distress risk and corporate failure forecasts.

Rezension

'This book provides a comprehensive and highly informative review of corporate distress and bankruptcy modelling literature. The book traces the early development of this literature from linear discriminant models that dominated bankruptcy research of the 1960s and 1970s to modern machine learning methods (such as gradient boosting machines and random forests) which have become more prevalent today. The book also provides a comprehensive illustration of different machine learning methods (such as gradient boosting machines and random forests) as well as several pointers in how to interpret and apply these models using a large international corporate bankruptcy dataset. A helpful book for all empirical researchers in academia as well as in business.'

Iftekhar Hasan, E. Gerald Corrigan Chair in International Business and Finance, Gabelli School of Business, Fordham University in New York, USA

'The corporate bankruptcy prediction literature has made rapid advances in recent years. This book provides a comprehensive and timely review of empirical research in the field. While the bankruptcy literature tends to be quite dense and mathematical, this book is very easy to read and follow. It provides a thorough but intuitive overview of a wide range of statistical learning methods used in corporate failure modelling, including multiple discriminant analysis, logistic regression, probit models, mixed logit and nested logit models, hazard models, neural networks, structural models of default and a variety of modern machine learning methods. The strengths and limitations of these methods are well illustrated and discussed throughout. This book will be a very useful compendium to anyone interested in distress risk and corporate failure modellin.'

Andreas Charitou, Professor of Accounting and Finance and Dean, School of Economics and Management, The University of Cyprus

'This is a very timely book that provides excellent coverage of the bankruptcy literature. Importantly, the discussion on machine learning methods is instructive, contemporary and relevant, given the increasingly widespread use of these methods in bankruptcy prediction and in finance and business more generally.'

Jonathan Batten, Professor of Finance, RMIT University

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

15.09.2022

Abbildungen

36 SW-Abb., 36 SW-Zeichn., 38 Tabellen

Verlag Taylor & Francis

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

15.09.2022

Abbildungen

36 SW-Abb., 36 SW-Zeichn., 38 Tabellen

Verlag Taylor & Francis
Seitenzahl

244

Maße (L/B/H)

23,4/15,6/1,3 cm

Gewicht

377 g

Sprache

Englisch

ISBN

978-1-138-65250-7

EU-Ansprechpartner

Taylor & Francis Verlag GmbH
Kaufingerstraße 24
80331 München
DE
GPSR@taylorandfrancis.com

Herstelleradresse

Taylor & Francis Group
5 Howick Place
SW1P 1WG London
UK
GPSR@taylorandfrancis.com

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

Die Leseprobe wird geladen.
  • Produktbild: Distress Risk and Corporate Failure Modelling
  • Produktbild: Distress Risk and Corporate Failure Modelling
  • 1. The Relevance and Utility of Distress Risk and Corporate Failure Forecasts 2. Searching for the Holy Grail: Alternative Statistical Modelling Approaches 3. The Rise of the Machines 4. An Empirical Application of Modern Machine Learning Methods 5. Corporate Failure Models for Private Companies, Not-for Profits, and Public Sector Entities 6. Whither Corporate Failure Research?