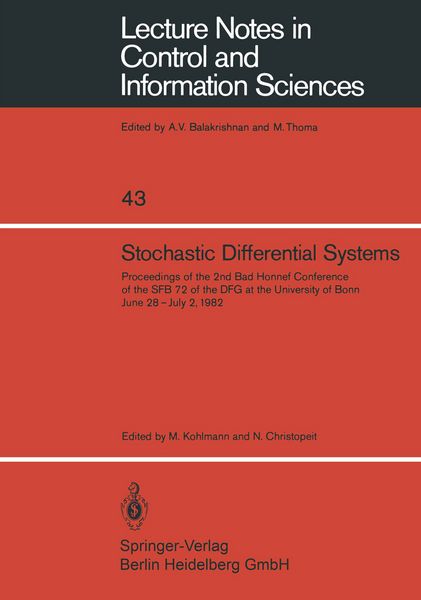
Stochastic Differential Systems Proceedings of the 2nd Bad Honnef Conference of the SFB 72 of the DFG at the University of Bonn June 28 – July 2, 1982
-
- Englisch ausgewählt
-
Verlag:Springer Berlin
49,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
01.11.1982
Abbildungen
XII, 381 p. 1 illus.
Herausgeber
M. Kohlmann + weitereVerlag
Springer BerlinSeitenzahl
381
Maße (L/B/H)
24,4/17/2,2 cm
Gewicht
681 g
Sprache
Englisch
ISBN
978-3-540-12061-2
Radon-Nikodym derivatives in case of rational spectral densities.- Differentiation of measures related to stochastic processes.- Dynkin games.- An introduction to the stochastic calculus of variations.- On one-dimensional Markov SDEs.- Some problems in sequential analysis.- A stochastic differential equation for Feller's one-dimensional diffusions.- A result of the iterated logarithm type for a certain class of stochastic processes.- Approximation of large deviations estimates and escape times and applications to systems with small noise effects.- On strong solutions of stohastic equations with respect to semimartingales.- Inverse problems in stochastic Riemannian geometry.- Some results on likelihood ratios for two-parameter processes.- Controllability of stochastic systems.- Solving the Zakai equation by ito's Method.- Simple and efficient linear and nonlinear filters by regular perturbation methods.- The non linear filtering equations.- On robust approximations in nonlinear filtering.- Smoothing of a diffusion process conditionned at final time.- First passage times in stochastic models of physical systems and in filtering theory.- Adaptive stochastic filtering problems - The continuous time case.- Between the chapters: An editor's note.- On perturbation methods in stochastic control.- A control problem in a manifold with nonsmooth boundary.- Some recent results on the control of partially observable stochastic systems.- Optimal controls for partially observed stochastic systems using nonstandard analysis.- Stochastic control with tracking of exogenous parameters.- Nisio semi-group associated to the control of Markov processes.- Optimal control of partially observed diffusions via the separation principle.- A class of singular stochastic control problems.- Surl'arret optimal de processus a deux indices reels.- Duality theory for some stochastic control models.- On the control of jump processes.- A partially observed inventory problem.- On impulsive control with long run average cost criterion.- Separation theorem for optimal impulse control with discontinuous observations.- Optimal control based on observations on the boundary.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für dein Feedback
Wir nutzen dein Feedback, um unsere Produktseiten zu verbessern. Bitte habe Verständnis, dass wir dir keine Rückmeldung geben können. Falls du Kontakt mit uns aufnehmen möchtest, kannst du dich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice