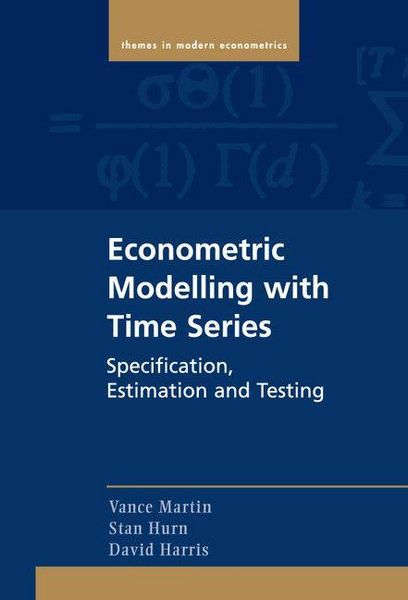
Econometric Modelling with Time Series
-
- Hardcover ausgewählt
- Taschenbuch
- eBook
-
Sprache:Englisch
226,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Gebundene Ausgabe
Erscheinungsdatum
06.02.2015
Abbildungen
104 b/w illus. 97 tables, Zeichnungen, nicht spezifiziert, Tabellen, nicht spezifiziert
Verlag
Cambridge AcademicSeitenzahl
924
Maße (L/B/H)
23,5/15,7/5,4 cm
Gewicht
1461 g
Sprache
Englisch
ISBN
978-0-521-19660-4
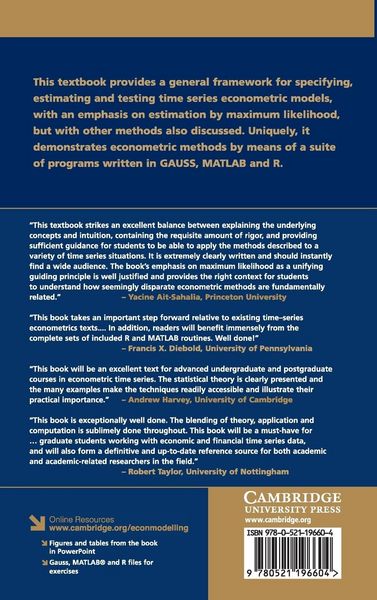
This book provides a general framework for specifying, estimating and testing time series econometric models. Special emphasis is given to estimation by maximum likelihood, but other methods are also discussed, including quasi-maximum likelihood estimation, generalised method of moments estimation, nonparametric estimation and estimation by simulation. An important advantage of adopting the principle of maximum likelihood as the unifying framework for the book is that many of the estimators and test statistics proposed in econometrics can be derived within a likelihood framework, thereby providing a coherent vehicle for understanding their properties and interrelationships. In contrast to many existing econometric textbooks, which deal mainly with the theoretical properties of estimators and test statistics through a theorem-proof presentation, this book squarely addresses implementation to provide direct conduits between the theory and applied work.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für dein Feedback
Wir nutzen dein Feedback, um unsere Produktseiten zu verbessern. Bitte habe Verständnis, dass wir dir keine Rückmeldung geben können. Falls du Kontakt mit uns aufnehmen möchtest, kannst du dich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice