An Introduction to Value-at-Risk, Fifth Edition
-
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
84,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
08.04.2013
Verlag
John Wiley & SonsSeitenzahl
224
Maße (L/B/H)
22,9/15,2/1,2 cm
Gewicht
335 g
Auflage
5th Revised edition
Sprache
Englisch
ISBN
978-1-118-31672-6
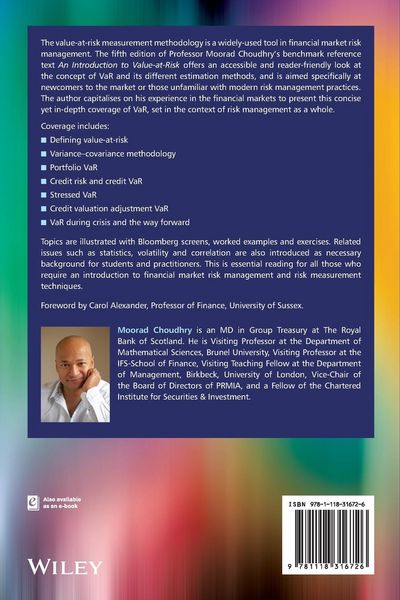
The value-at-risk measurement methodology is a widely-used tool in financial market risk management. The fifth edition of Professor Moorad Choudhry's benchmark reference text An Introduction to Value-at-Risk offers an accessible and reader-friendly look at the concept of VaR and its different estimation methods, and is aimed specifically at newcomers to the market or those unfamiliar with modern risk management practices. The author capitalises on his experience in the financial markets to present this concise yet in-depth coverage of VaR, set in the context of risk management as a whole.
Topics covered include:
- Defining value-at-risk
- Variance-covariance methodology
- Portfolio VaR
- Credit risk and credit VaR
- Stressed VaR
- Critique and VaR during crisis
Topics are illustrated with Bloomberg screens, worked examples and exercises. Related issues such as statistics, volatility and correlation are also introduced as necessary background for students and practitioners. This is essential reading for all those who require an introduction to financial market risk management and risk measurement techniques.
Foreword by Carol Alexander, Professor of Finance, University of Sussex.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für dein Feedback
Wir nutzen dein Feedback, um unsere Produktseiten zu verbessern. Bitte habe Verständnis, dass wir dir keine Rückmeldung geben können. Falls du Kontakt mit uns aufnehmen möchtest, kannst du dich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice