KI-Beratung Beta

  • Produktbild: Elementary Probability Theory
  • Produktbild: Elementary Probability Theory

Elementary Probability Theory With Stochastic Processes and an Introduction to Mathematical Finance

64,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

In this edition two new chapters, 9 and 10, on mathematical finance are added. They are written by Dr. Farid AitSahlia, ancien eleve, who has taught such a course and worked on the research staff of several industrial and financial institutions. The new text begins with a meticulous account of the uncommon...

Beschreibung

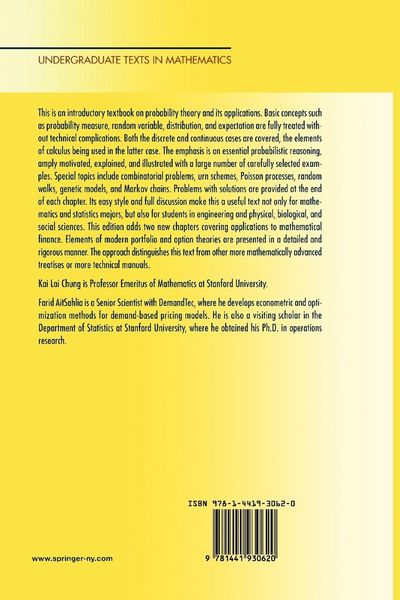
In this edition two new chapters, 9 and 10, on mathematical finance are added. They are written by Dr. Farid AitSahlia, ancien eleve, who has taught such a course and worked on the research staff of several industrial and financial institutions. The new text begins with a meticulous account of the uncommon vocab ulary and syntax of the financial world; its manifold options and actions, with consequent expectations and variations, in the marketplace. These are then expounded in clear, precise mathematical terms and treated by the methods of probability developed in the earlier chapters. Numerous graded and motivated examples and exercises are supplied to illustrate the appli cability of the fundamental concepts and techniques to concrete financial problems. For the reader whose main interest is in finance, only a portion of the first eight chapters is a "prerequisite" for the study of the last two chapters. Further specific references may be scanned from the topics listed in the Index, then pursued in more detail.

Rezension

"In spite of the original edition of the book being nearly thirty years old, the text still has its role to play in first and second year undergraduate probability courses. It provides an excellent foundation to more advanced courses in the subject."
Short Book Reviews, Vol. 23/3, Dec. 2003

"This edition is the third revision of a text on mathematical probability first published in 1974. The text is aimed at undergraduate mathematics students and is accessible to a general audience. The prose is accurate, entertaining, and dense with historical tidbits. Two concluding chapters on mathematical finance have been added to the eight chapters in the third edition by the second author." The American Statistician, May 2004

From the reviews of the fourth edition:

"The main novelty in the fourth edition of this well-written book is the addition of new chapters … . The new chapters share the friendly yet rigorous style of the former ones. They beginwith an account of the financial vocabulary, which is then expounded in probabilistic terms. … Almost thirty years after its first edition, this charming book continues to be an excellent text for teaching and for self study." (Ricardo Maronna, Statistical Papers, Vol. 45 (4), 2004)

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

01.12.2010

Abbildungen

XIV, 404 p.

Verlag Springer Us

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

01.12.2010

Abbildungen

XIV, 404 p.

Verlag Springer Us
Seitenzahl

404

Maße (L/B/H)

23,5/15,5/2,3 cm

Gewicht

633 g

Auflage

Fourth Edition 2003

Sprache

Englisch

ISBN

978-1-4419-3062-0

Herstelleradresse

Springer-Verlag KG
Sachsenplatz 4-6
1201 Wien
AT

Email: ProductSafety@springernature.com

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Elementary Probability Theory
  • Produktbild: Elementary Probability Theory
  • 1 Set.- 1.1 Sample sets.- 1.2 Operations with sets.- 1.3 Various relations.- 1.4 Indicator.- Exercises.- 2 Probability.- 2.1 Examples of probability.- 2.2 Definition and illustrations.- 2.3 Deductions from the axioms.- 2.4 Independent events.- 2.5 Arithmetical density.- Exercises.- 3 Counting.- 3.1 Fundamental rule.- 3.2 Diverse ways of sampling.- 3.3 Allocation models; binomial coefficients.- 3.4 How to solve it.- Exercises.- 4 Random Variables.- 4.1 What is a random variable?.- 4.2 How do random variables come about?.- 4.3 Distribution and expectation.- 4.4 Integer-valued random variables.- 4.5 Random variables with densities.- 4.6 General case.- Exercises.- Appendix 1: Borel Fields and General Random Variables.- 5 Conditioning and Independence.- 5.1 Examples of conditioning.- 5.2 Basic formulas.- 5.3 Sequential sampling.- 5.4 Pólya’s urn scheme.- 5.5 Independence and relevance.- 5.6 Genetical models.- Exercises.- 6 Mean, Variance, and Transforms.- 6.1 Basic properties of expectation.- 6.2 The density case.- 6.3 Multiplication theorem; variance and covariance.- 6.4 Multinomial distribution.- 6.5 Generating function and the like.- Exercises.- 7 Poisson and Normal Distributions.- 7.1 Models for Poisson distribution.- 7.2 Poisson process.- 7.3 From binomial to normal.- 7.4 Normal distribution.- 7.5 Central limit theorem.- 7.6 Law of large numbers.- Exercises.- Appendix 2: Stirling’s Formula and de Moivre-Laplace’ Theorem.- 8 From Random Walks to Markov Chains.- 8.1 Problems of the wanderer or gambler.- 8.2 Limiting schemes.- 8.3 Transition probabilities.- 8.4 Basic structure of Markov chains.- 8.5 Further developments.- 8.6 Steady state.- 8.7 Winding up (or down?).- Exercises.- Appendix 3: Martingale.- 9 Mean-Variance Pricing Model.- 9.1 An investments primer.- 9.2 Asset return and risk.- 9.3 Portfolio allocation.- 9.4 Diversification.- 9.5 Mean-variance optimization.- 9.6 Asset return distributions.- 9.7 Stable probability distributions.- Exercises.- Appendix 4: Pareto and Stable Laws.- 10 Option Pricing Theory.- 10.1 Options basics.- 10.2 Arbitrage-free pricing: 1-period model.- 10.3 Arbitrage-free pricing: N-period model.- 10.4 Fundamental asset pricing theorems.- Exercises.- General References.- Answers to Problems.- Values of the Standard Normal Distribution Function.