KI-Beratung Beta

  • Produktbild: Time Series Models
  • Produktbild: Time Series Models
- 12%

Time Series Models In econometrics, finance and other fields

12% sparen

74,99 € UVP 85,59 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

The analysis prediction and interpolation of economic and other time series has a long history and many applications. Major new developments are taking place, driven partly by the need to analyze financial data. The five papers in this book describe those new developments from various viewpoints and...

Beschreibung

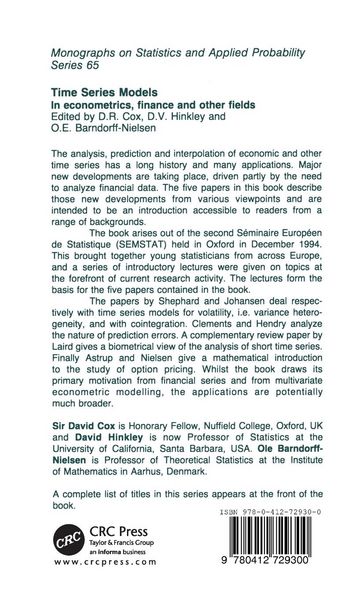
The analysis prediction and interpolation of economic and other time series has a long history and many applications. Major new developments are taking place, driven partly by the need to analyze financial data. The five papers in this book describe those new developments from various viewpoints and are intended to be an introduction accessible to readers from a range of backgrounds.
The book arises out of the second Seminaire European de Statistique (SEMSTAT) held in Oxford in December 1994. This brought together young statisticians from across Europe, and a series of introductory lectures were given on topics at the forefront of current research activity. The lectures form the basis for the five papers contained in the book.
The papers by Shephard and Johansen deal respectively with time series models for volatility, i.e. variance heterogeneity, and with cointegration. Clements and Hendry analyze the nature of prediction errors. A complementary review paper by Laird gives a biometrical view of the analysis of short time series. Finally Astrup and Nielsen give a mathematical introduction to the study of option pricing. Whilst the book draws its primary motivation from financial series and from multivariate econometric modelling, the applications are potentially much broader.

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

15.05.1996

Abbildungen

49 SW-Abb.,

Herausgeber D. R. Cox + weitere

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

15.05.1996

Abbildungen

49 SW-Abb.,

Herausgeber
Verlag Springer Netherlands
Seitenzahl

242

Maße (L/B/H)

22,2/14,5/1,7 cm

Gewicht

381 g

Auflage

Softcover reprint of the original 1st ed. 1996

Sprache

Englisch

ISBN

978-0-412-72930-0

Herstelleradresse

Libri GmbH
Europaallee 1
36244 Bad Hersfeld
DE

Email: gpsr@libri.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

Die Leseprobe wird geladen.
  • Produktbild: Time Series Models
  • Produktbild: Time Series Models
  • Statistical Aspects of ARCH and Scholastic Volatility
    Likelihood-Based Inference for Cointegration of Some Non-Stationary Time Series
    Forecasting in Macroeconomics
    Longitudinal Panel Data: An Overview of Current Methodology