KI-Beratung Beta

  • Produktbild: High Dimensional Probability II
  • Produktbild: High Dimensional Probability II
Band 47 - 13%

High Dimensional Probability II

Aus der Reihe Progress in Probability
13% sparen

138,99 € UVP 160,49 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

29.09.2000

Abbildungen

XI, 512 p.

Herausgeber

Evarist Giné + weitere

Verlag

Birkhäuser Boston

Seitenzahl

512

Maße (L/B/H)

23,4/15,6/2,9 cm

Gewicht

912 g

Auflage

2000 edition

Sprache

Englisch

ISBN

978-0-8176-4160-3

Beschreibung

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

29.09.2000

Abbildungen

XI, 512 p.

Herausgeber

Verlag

Birkhäuser Boston

Seitenzahl

512

Maße (L/B/H)

23,4/15,6/2,9 cm

Gewicht

912 g

Auflage

2000 edition

Sprache

Englisch

ISBN

978-0-8176-4160-3

Herstelleradresse

Libri GmbH
Europaallee 1
36244 Bad Hersfeld
DE

Email: gpsr@libri.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: High Dimensional Probability II
  • Produktbild: High Dimensional Probability II
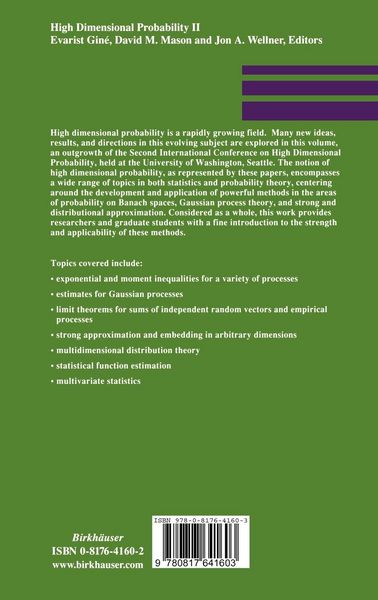
  • Moment Bounds for Self-Normalized Martingales.- Exponential and Moment Inequalities for U-Statistics.- A Multiplicative Inequality for Concentration Functions of n-Fold Convolutions.- On Exact Maximal Khinchine Inequalities.- Strong Exponential Integrability of Martingales with Increments Bounded by a Sequence of Numbers.- On Uniform Laws of Large Numbers for Smoothed Empirical Measures.- Weak Convergence of Smoothed Empirical Processes: Beyond Donsker Classes.- Limit Theorems for Smoothed Empirical Processes.- Preservation Theorems for Glivenko-Cantelli and Uniform Glivenko-Cantelli Classes.- Continuité de certaines fonctions aléatoires gaussiennes à valeurs dans lp, 1?pof Cross Validation for Spline Smoothing.- Rademacher Processes and Bounding the Risk of Function Learning.- Bootstrapping Empirical Distributions under Auxiliary Information.- On the Characteristic Function of the Matrix von Mises-Fisher Distribution with Application to SO(N)—Deconvolution.- Testing for Ellipsoidal Symmetry of a Multivariate Distribution.